Ordinance or law coverage can help pay extra rebuild costs when a South Carolina or North Carolina home must meet current codes after a covered homeowners loss. Dwelling Coverage A pays to restore the house as it stood, so code-upgrade work needs a separate limit, not a flood policy or a named-storm deductible.
Most Carolina homeowners policies do not automatically pay for sewer or drain backup. Water backup coverage is usually a chosen-limit add-on, and it is not a substitute for flood insurance.
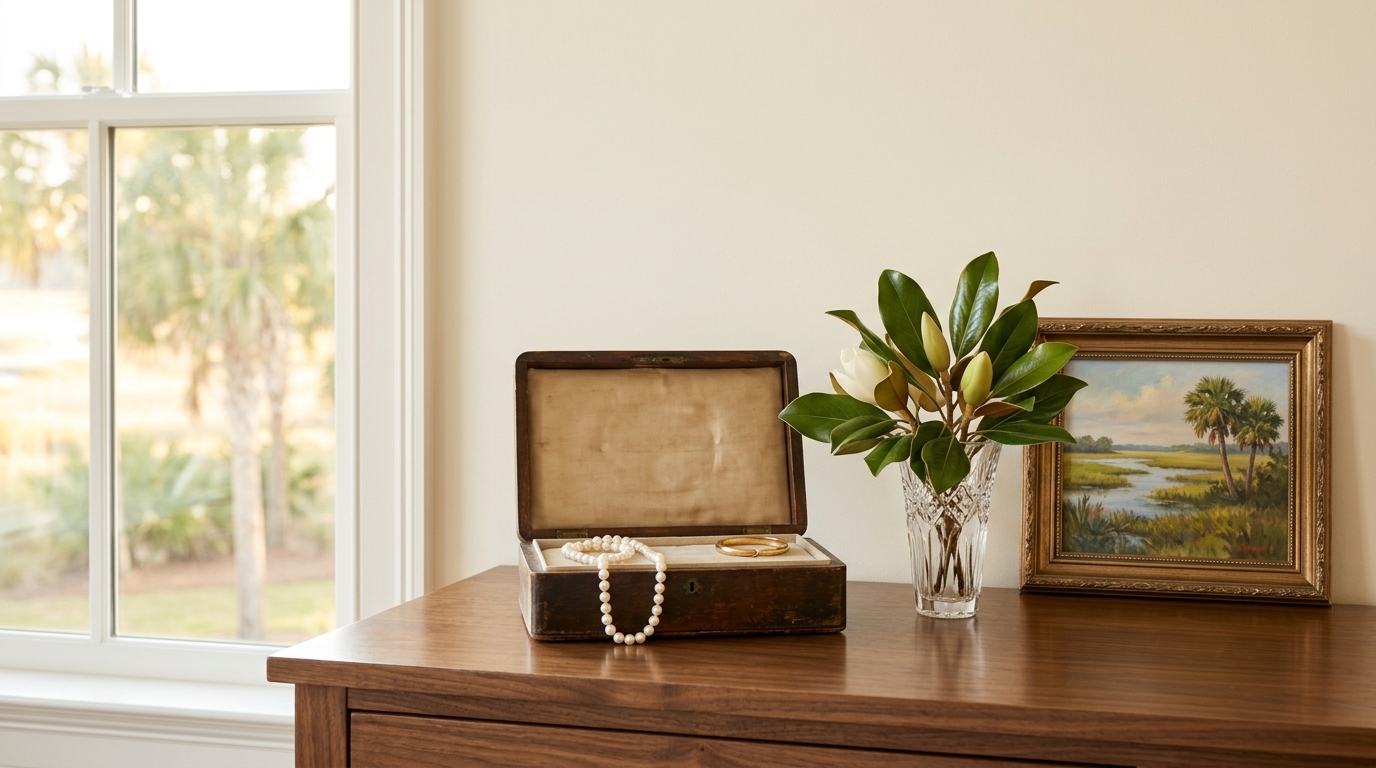
A standard homeowners policy in North Carolina or South Carolina covers jewelry, art, and collections, but special limits are often far below replacement cost. Scheduled personal property jewelry coverage lists those items at an agreed or appraised amount and can follow them off the premises.