A 2022 ISO HO-3 in the Carolinas usually caps property used primarily for business at $3,000 on the residence premises and $1,500 away, and it excludes injury arising out of a business conducted from the home. HO 04 12 can raise the property cap; HO 07 01 can add property, income, and liability for an eligible owned practice, but not professional liability.
Hail on a typical Carolina HO-3 can trigger dwelling coverage, but the check size depends on roof age, replacement cost versus actual cash value, and whether a matching endorsement was added. Neither South Carolina nor North Carolina requires a carrier to replace undamaged shingles so the roof matches.
Service line coverage homeowners Carolinas can add is an optional endorsement for buried water, sewer, electric, gas, and communication lines on the premises. It is not part of a typical unendorsed homeowners form, and it does not replace water backup coverage or flood insurance.
Wind mitigation credits Carolina homeowners can use in South Carolina and North Carolina depend on inspectable roof, opening, and structural upgrades. Credits, when filed, attach to the wind or wind-and-hail portion of a homeowners premium and vary by carrier, territory, and verified features.
Ordinance or law coverage can help pay extra rebuild costs when a South Carolina or North Carolina home must meet current codes after a covered homeowners loss. Dwelling Coverage A pays to restore the house as it stood, so code-upgrade work needs a separate limit, not a flood policy or a named-storm deductible.
Most Carolina homeowners policies do not automatically pay for sewer or drain backup. Water backup coverage is usually a chosen-limit add-on, and it is not a substitute for flood insurance.
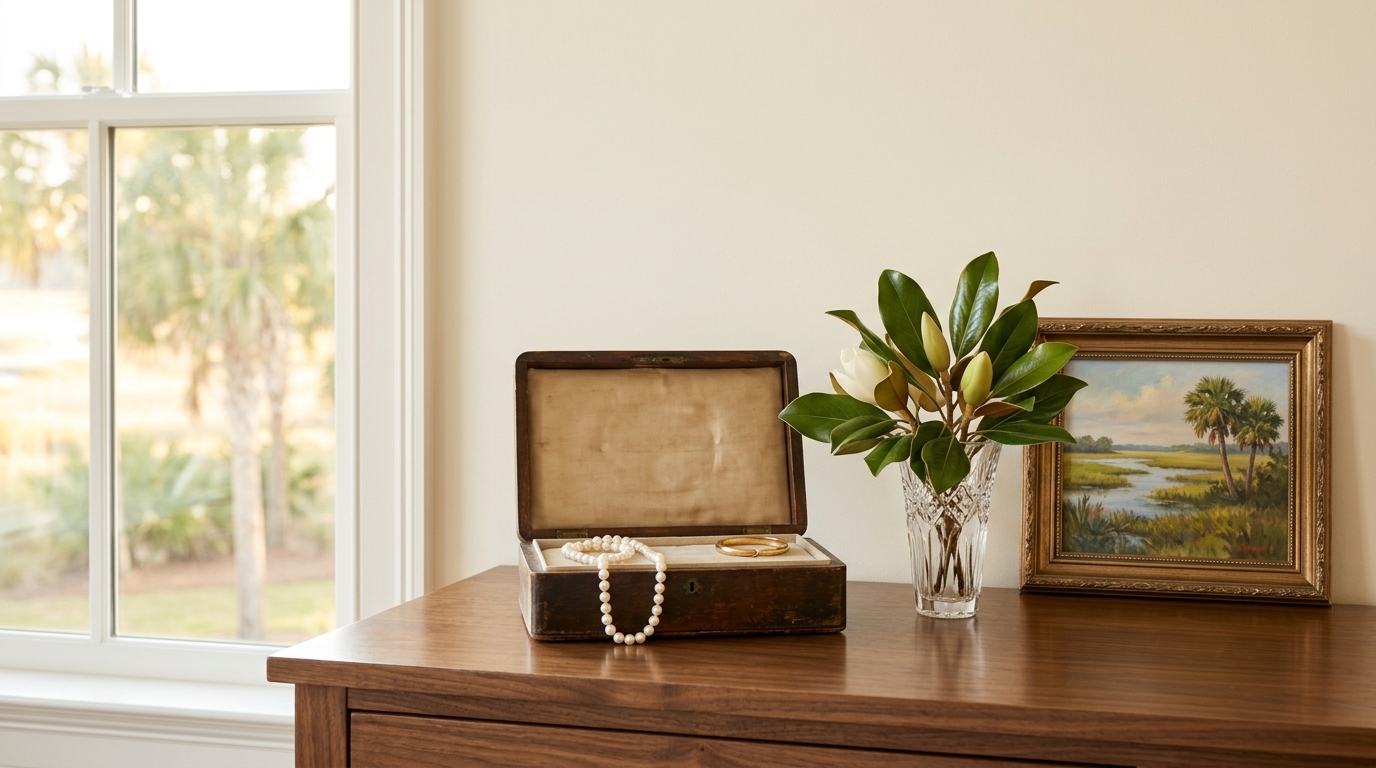
A standard homeowners policy in North Carolina or South Carolina covers jewelry, art, and collections, but special limits are often far below replacement cost. Scheduled personal property jewelry coverage lists those items at an agreed or appraised amount and can follow them off the premises.
Listing a Myrtle Beach or coastal vacation home for short stays often requires more than a standard homeowners policy. Learn how endorsements, landlord or specialty forms, platform programs, and flood cover fit real hosting use.